Expense Management

A prepaid card spends money you load in advance. A debit card spends directly from your bank account. A credit card spends the issuer's money and you repay later. A corporate card is a company card issued to employees, with limits and controls set by the business. Virtual cards aren't a separate funding type: they're card numbers without the plastic, which you can create in seconds for online spend.
If you run a business in Malaysia, you've probably been told to pick one card and stick with it. That advice quietly costs you money. These cards do different jobs, and the businesses that spend well match each payment to the card built for it.
The first question is where the money comes from. That's the difference between prepaid, debit, credit and charge cards: money loaded in advance, money in your bank account, or money the issuer lends you.
The second question is what form the card takes: physical or virtual. That has nothing to do with funding. A virtual card is a card number with no plastic, and it can sit on top of almost any account.
Answer both for each payment and you land on the right card every time.
A prepaid card holds money you've loaded onto it before you spend. When the balance runs out, the card stops. There's no borrowing, no interest and no link to your main bank account, so it's a common way to give someone a fixed budget. Bank Negara Malaysia describes this kind of stored value as money that has been "paid in advance by the user".[1]
Businesses use prepaid cards for per-diems, team trips and one-off budgets. The trade-off is acceptance: some online platforms and subscription services turn prepaid cards away, so they're not the card for spend that simply has to go through.
A debit card takes the amount "directly from the cardholder's bank account". A credit card lets you buy "with a credit line given by the credit card issuer". A charge card also lends you the money, but you "settle the outstanding amount in full" every month.[1] Here's how they compare for a business.
| Card type | Money comes from | Credit check | Best for | Watch out for |
|---|---|---|---|---|
| Prepaid | Money you load in advance | Usually not | Fixed budgets, travel, per-diems | Some online platforms decline it |
| Debit | Your bank account | No, but you need the bank account | Everyday spend by the account holder | Fraud hits your main account; hard to share with staff |
| Credit | The issuer's credit line, repaid later | Yes; business cards often ask for 2+ years of trading | Spreading cash flow, bank rewards | Interest on unpaid balances, annual fees |
| Charge | The issuer, settled in full each month | Yes | Large monthly spend paid off in one go | Late charges if not settled on time |
| Corporate | Depends on the issuer: credit, charge or prefunded | Depends on the issuer | Team spend with per-person limits | Check controls, fees and what syncs to your books |
A virtual card is a card number created digitally. You can issue one in seconds, use it online straight away, and freeze or delete it just as fast. Give each subscription or vendor its own virtual card and one leaked number, or one surprise price rise, stays on one card while the rest keep working.
A physical card is still the right call when someone has to tap at a terminal or withdraw cash, usually on the road.
A corporate card is a card the company issues to employees for business spend. The business sets the rules: who gets a card, how much each person can spend, and where. Unlike a director's personal card or a single shared debit card, every transaction is tied to a person and a purpose, which is what makes month-end bearable.
How it's funded depends on the provider. Bank corporate cards usually run on a credit or charge line, which means credit checks and trading-history requirements. Newer providers prefund cards from a company balance instead. For a side-by-side of the options, see our guide to the best business and corporate cards in Malaysia.
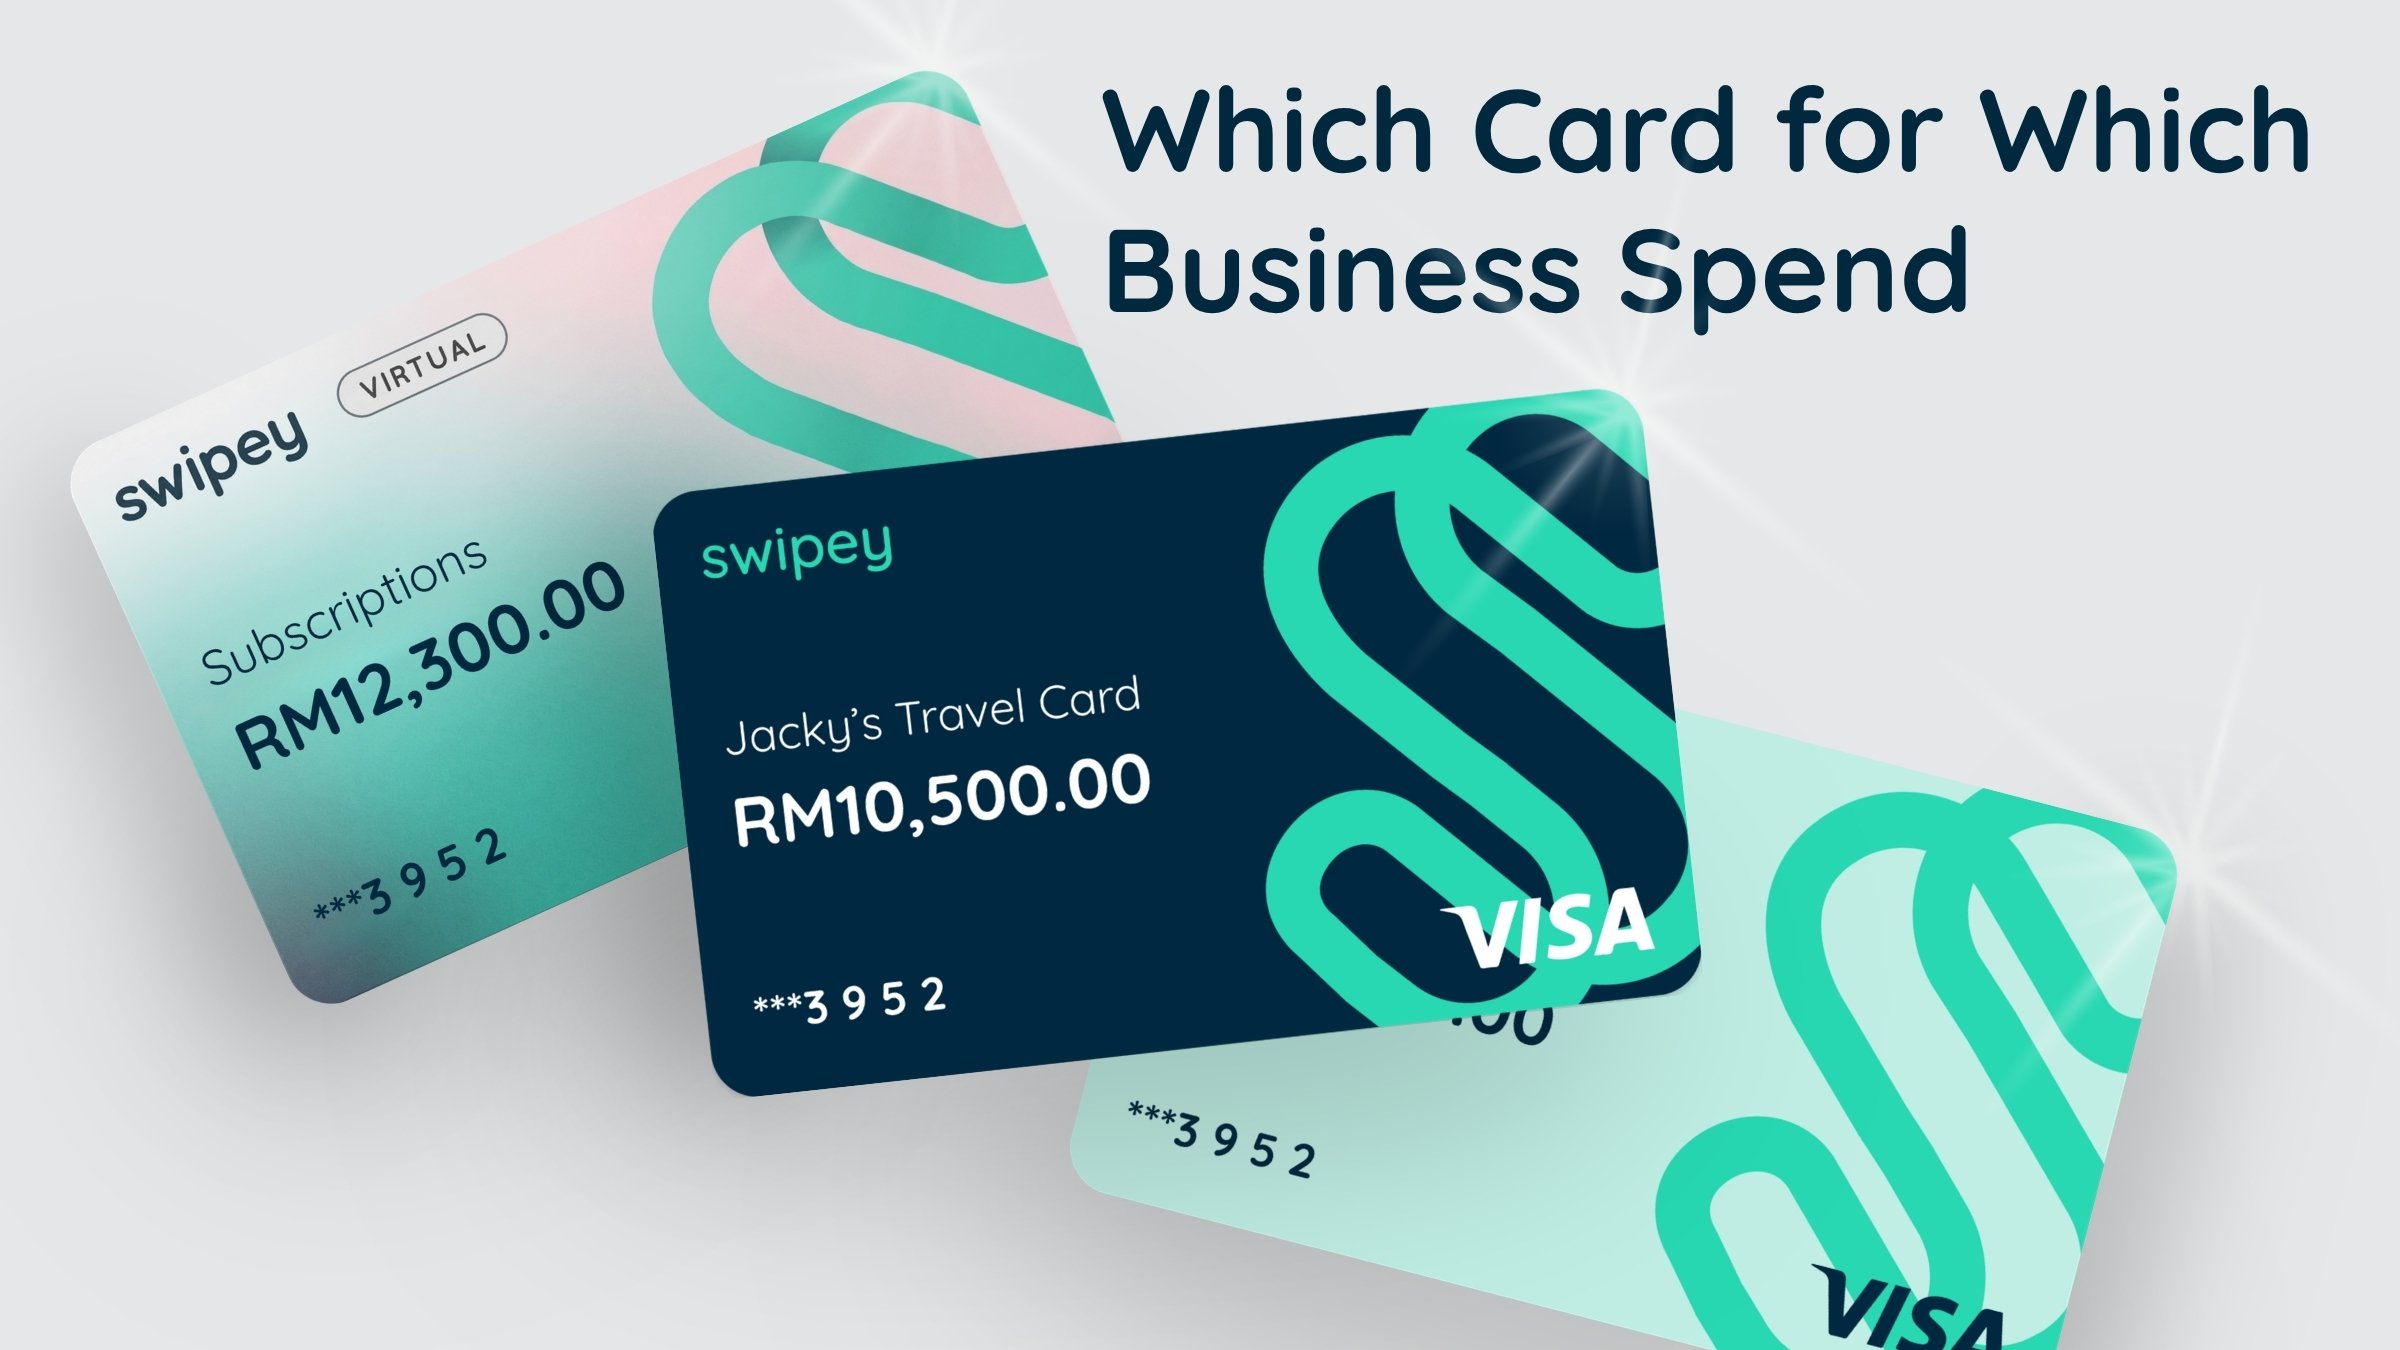
Compare all three Swipey cards
Match the spend to the job, not to a category. For a typical Malaysian business, it usually works out like this.
| Spend | Card that fits | On Swipey | Why |
|---|---|---|---|
| Google Ads, OpenAI, Microsoft, Azure | Virtual corporate card | Corporate Card | Campaigns and cloud bills keep running, with one card per platform |
| SaaS and online subscriptions | One virtual card per tool | Corporate Card | Nothing lapses, a leak stays on one card, and eligible spend earns cashback |
| One-off campaign or project budget | Virtual card with a fixed limit | Corporate Card | Set the ceiling up front so the budget can't be overshot |
| Local suppliers, parking, meals | Per-person card that pays DuitNow QR | Virtual Card - QR Enabled | Staff pay from a company budget, not their own pocket, so there are no claims to chase |
| Business trips, at home or overseas | Physical card with a trip budget | Travel Card | Tap in store and withdraw cash, within the budget you set |
None of these is the "bad" card. The expensive mistake is putting the wrong spend on the wrong card. An ad account that gets declined mid-campaign stops your leads overnight (here's how to fix a declined card on Google Ads or OpenAI). A trip budget on an open card with no ceiling invites overspend. Get the match right and each card does the thing it's good at.
Most business finance tools are built for one slice of this, usually moving money across borders. Swipey is built for the rest of your week: paying suppliers by DuitNow QR, keeping ads and cloud bills running, and closing the books without the month-end scramble.
Every card feeds one dashboard, receipts are matched to transactions as you spend, and it all syncs to Bukku, Xero or QuickBooks. That's how teams on Swipey close their books 12x faster.
Want the full picture? Download the Swipey overview deck.
Spend you want capped: travel, per-diems, gifts and one-off budgets. You load a set amount and the card stops when it's used up, so there's no overspend and no interest.
No. A debit card spends straight from your bank account. A prepaid card spends only the balance loaded onto it, so it isn't linked to your main account. They can look the same at checkout because both often run on Visa or Mastercard.
Yes, and often safer than one shared physical card. Each virtual card has its own number and limit, there's no plastic to lose, and you can freeze or delete one card instantly without touching the others.
Yes. Several banks and payment providers offer prepaid or prefunded business cards.
On Swipey, any business registered in Malaysia, including sole proprietors, can sign up and issue cards to the team.
No. Swipey doesn't offer credit cards, and it's for business use only. The Corporate Card is prefunded: you top up your company's Swipey balance and cards spend from it, so there's no interest and no bill to repay.
Corporate Card for online spend, Virtual Card - QR Enabled for DuitNow QR, Travel Card for trips. One dashboard, synced to your books. Trusted by 4,000+ Malaysian businesses.