The short answer
A business credit card lends you the bank's money up to a limit, charges interest if you don't repay in full, and usually needs a few years of trading history. A corporate card like Swipey spends your company's own balance, gives each employee or tool its own card with a set limit, and syncs every transaction to your accounting software. Pick credit when you need a credit line. Pick a corporate card when you need control over team spend.
They look the same at checkout, so the choice often gets made by default: whichever card the director already has. But they solve different problems, and the wrong one costs you in interest, in lost control or in month-end hours.
How a business credit card works
The bank gives your company a credit limit. You spend up to it, get a monthly statement, and either pay in full or carry a balance and pay interest. Banks assess your business before approving, so most ask for a track record: CIMB's SME BusinessCard, for example, needs at least two years in operation.[1]
The upside is float: you can spend now and pay later, and many cards pay cash rebates. The trade-off is that cards are usually issued to a few named people, spend lands on one statement, and someone still has to match every line to a receipt.
How a corporate card works
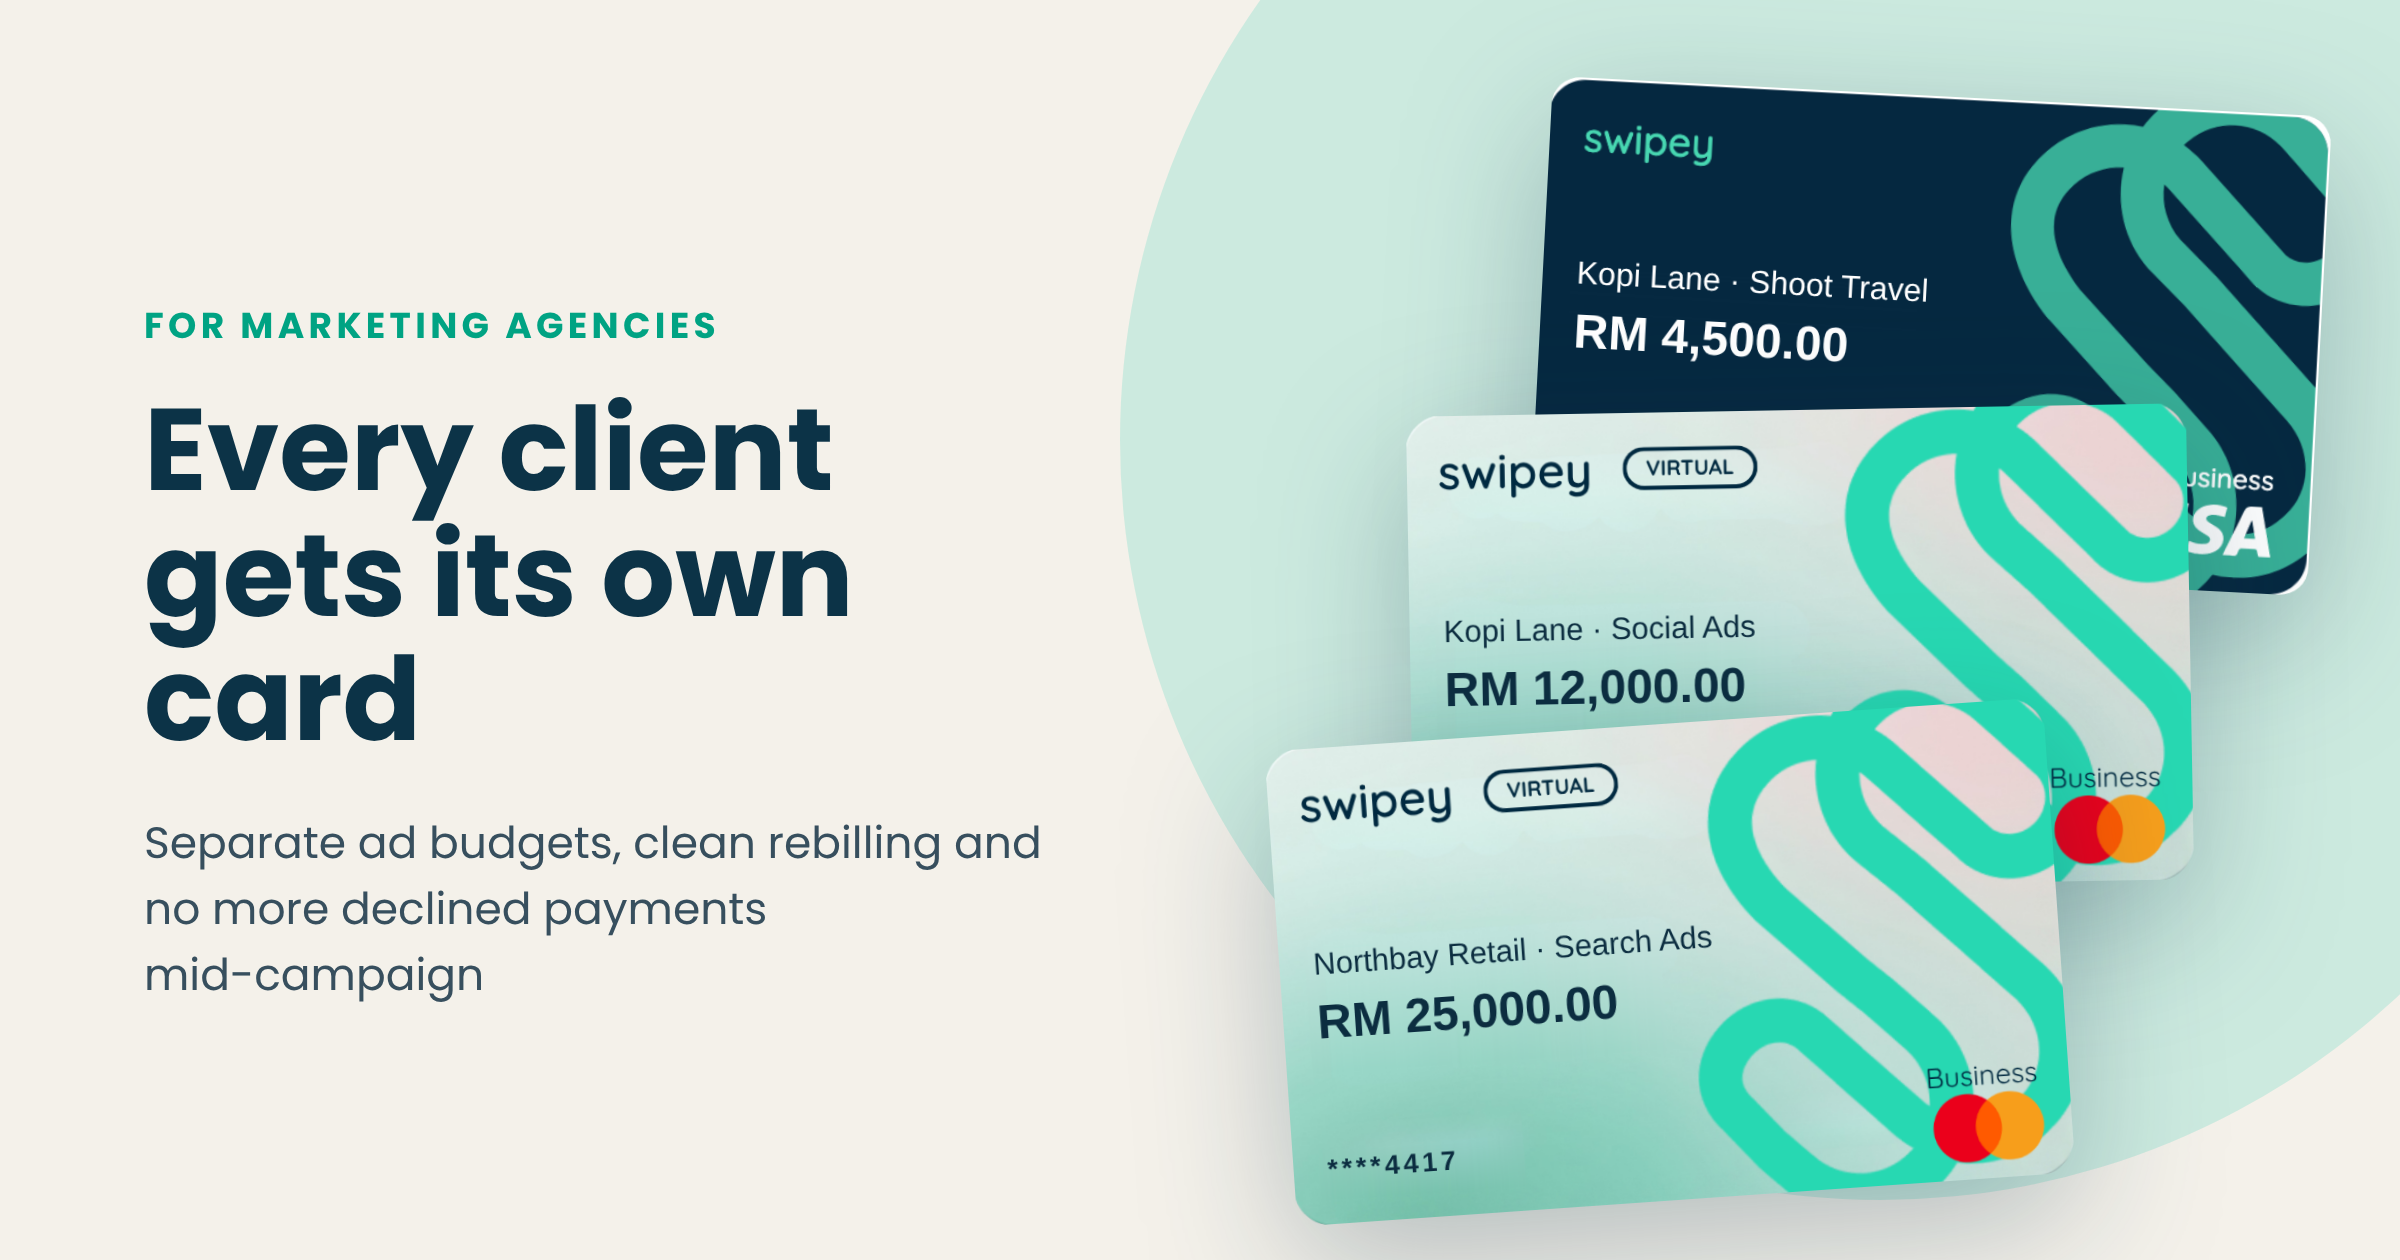
A corporate card is built around the team, not the account holder. With Swipey, you top up your company's balance and issue cards from it: one per employee, tool, campaign or project, each with its own limit. There's no credit line, so there's no interest and no repayment bill.
Every transaction is tied to a card and a person. Receipts are matched as staff spend, and everything syncs to Bukku, Xero or QuickBooks, which is how teams on Swipey close their books 12x faster.
Side by side: Swipey Corporate Card vs CIMB SME BusinessCard
To keep it concrete, here's Swipey against one of Malaysia's best-known business credit cards. Terms as published on 3 November 2026.
| |
CIMB SME BusinessCard |
Swipey Corporate Card |
| Money comes from |
The bank's credit line |
Your company's Swipey balance |
| Interest |
15–18% a year on unpaid balances |
None, there's nothing to repay |
| Who can apply |
Businesses 2+ years in operation |
Any Malaysian-registered business, including sole proprietors |
| Annual fee |
Waived, RM25 service tax per card a year |
Free, cards and users unlimited (see all fees) |
| Cashback |
0.5% local, 1.25% overseas |
1.1% on eligible software, subscription and online business services spend, no monthly cap per company |
| Cards for staff |
Issued to named cardholders under the bank's approval |
A card per employee, tool or campaign, created in the app |
| Limits |
Credit limit set by the bank |
You set a limit per card, and can freeze any card instantly |
| Overseas spend |
Mastercard rate + 1% |
Card-network fee on merchants outside Malaysia (details) |
| Accounting |
Monthly statement, matched by hand |
Receipts matched as you spend, synced to Bukku, Xero or QuickBooks |
CIMB terms from its product page and fees schedule (sources 1 and 2). Swipey cashback runs 1 October 2026 to 30 June 2027, terms apply.
Which one wins, and when
A bank credit card makes more sense when
- you need a credit line to smooth cash flow between invoices
- only one or two directors spend on behalf of the company
- most of your spend is overseas travel, where bank rebates are strongest
A corporate card makes more sense when
- several people or teams spend, and each needs a budget
- you pay for ads, SaaS, AI and cloud tools, each better on its own card
- your company is too new for a bank card, or you'd rather not carry debt
- month-end matching is eating days your finance team doesn't have
Can you use both?
Yes, and many growing companies do. Keep the bank card for what it's good at, a credit line and the director's big-ticket travel. Move team spend and online tools onto corporate cards, where each one has an owner, a limit and a receipt attached.
A good first move is the spend that hurts most on a shared card: Google Ads, OpenAI, Microsoft and Azure, which the Swipey Corporate Card keeps running without declines. For a wider look at every option, see our guide to the best business and corporate cards in Malaysia, or how prepaid, debit, credit and corporate cards compare.
FAQ
Is a corporate card a credit card?
Not necessarily. Some banks issue corporate cards on a credit line. Swipey doesn't offer credit cards: its Corporate Card spends your company's own balance, so there's no interest and no repayment bill.
Do I need years of trading history for a corporate card?
Not with Swipey. Any business registered in Malaysia can sign up, including new companies. Bank business credit cards usually ask for a track record, such as two years in operation for CIMB's SME BusinessCard.
Which is better for overseas spending?
For overseas travel, bank cards with overseas rebates are hard to beat. For online tools billed from overseas, like ads, SaaS and cloud, a corporate card gives each tool its own card and limit and keeps the spend in your books automatically.
Can sole proprietors get one?
Yes. Any Malaysian-registered business can sign up for Swipey, including sole proprietors.
Give your team cards without a credit line
A Corporate Card per person or tool, a limit on each, and books that close themselves. Trusted by 4,000+ Malaysian businesses.